Let’s get the disclosure out of the way.
I’m a finance guy. I’ve been a CFO. I’ve been a COO. I’ve spent decades in the back office, the part of the company where the printer only works if you talk to it nicely.
So when I tell you operations is the most important thing a scaling business can invest in, you should take that with the same grain of salt you’d take from a dentist explaining why you should floss.
The dentist is still right, by the way. And so am I.
The departments nobody claps for
Every company has a front of the house and a back of the house.
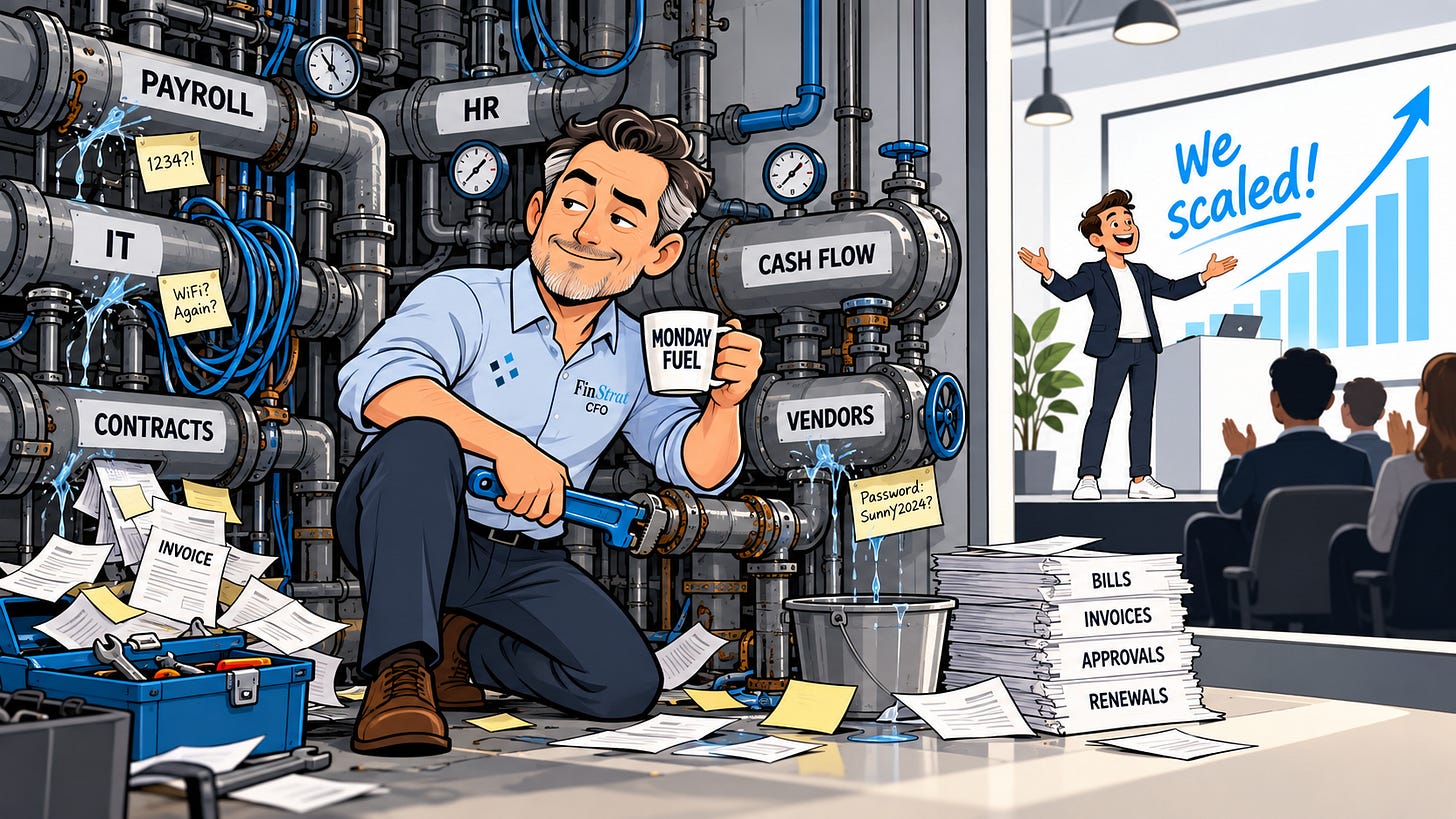
The front gets the glory. Sales rings the bell. The creative team wins the award. The founder gives the keynote and gets a nice photo on stage with dramatic lighting.
The back of the house gets an email asking why the Wi-Fi is down.
When I say operations, I mean four things:
→ Finance. The money. Where it comes from, where it goes, and whether anyone’s writing it down correctly.
→ IT. The systems, the security, the laptops, and the passwords currently living on a sticky note under someone’s keyboard.
→ HR. Hiring, onboarding, pay, benefits, policies, and making sure people don’t get lost in the shuffle.
→ Admin. Contracts, insurance, vendors, leases, calendars. The glue that holds the other three together.
These four have one thing in common. Nobody notices when they work. They’re like plumbing. You don’t wake up grateful that your toilet flushed. You just expect it to. Then one day it doesn’t, and suddenly plumbing is the only thing anyone in the house can talk about.
Why it breaks when you grow
At ten people, a founder can run operations from memory.
You know who’s paid what. You know where the contracts are, mostly. You sign every check. You set up the laptops yourself on a Sunday, while muttering.
At thirty people, memory starts to fail. Things live in three places, or in one person’s head, or in a folder called “New Folder (2).”
At sixty people, nobody’s quite sure who’s responsible for what, and the answer to most questions is “ask Linda,” and Linda’s been on vacation for a week, and the company’s slowly grinding to a halt like a cruise ship that ran out of buffet.
Growth doesn’t create operational problems. It exposes the ones you already had. The cracks were always there. Revenue just put more weight on them.
When finance fails, you get messy books.
Not dramatic-messy. Quiet-messy. Expenses coded wherever was convenient. Bank accounts that haven’t been reconciled since the spring. Revenue recorded when the cash shows up instead of when the work was done. A balance sheet nobody’s opened since the bank last asked.
And messy books don’t stay in the books. They travel.
They travel to your tax return. Your CPA prepares your taxes from the books you give them. If the books are wrong, the return is wrong, and now you’ve got an erroneous tax return with your signature on it. Your CPA’s very good. They’re not psychic.
They travel to your decisions. You can’t price work if you don’t know what it costs to deliver. You can’t plan a hire if you don’t know what next quarter looks like.
Which brings me to capacity planning, the most important thing almost nobody does. Who’s free next month? Which team’s drowning? Can you take on that new client without everyone working weekends until spring? If finance and operations aren’t talking, the honest answer to all of those questions is a shrug. An expensive shrug.
When finance fails, you also get fraud.
Nobody likes this part. Everyone thinks it won’t happen to them, because they trust their people.
That trust is exactly the problem.
The Association of Certified Fraud Examiners publishes a big study on this every two years. Their 2026 report found that small businesses, meaning fewer than 100 employees, had the highest median fraud loss of any size group: $126,000 per case. More than half of all the cases happened because of missing internal controls, or controls someone simply overrode. And the typical fraud ran for a full year before anyone caught it.
A full year. Of someone quietly paying themselves out of your business while you’re in a strategy meeting about brand positioning.
It’s almost never a criminal mastermind. It’s usually someone you like, with too much access and nobody checking. The same person creates vendors, approves invoices and sends the payments. That’s not a process. That’s an honor system with a bank account attached.
When IT fails, you find out at the worst possible time.
The employee who left eight months ago still has access to every system you own. The backup you thought was running stopped in March. The passwords are in a spreadsheet called “Passwords,” which, to be fair, is easy to find. For everyone.
Then there’s the new stuff. AI is an instrument, and in the wrong hands it can play your CEO’s voice well enough to fool your controller into sending a wire. If nobody owns IT and security, nobody’s thinking about that. The scammers definitely are.
And in a lot of growing companies, the IT department is someone’s very helpful nephew who’s good with computers and currently backpacking through Portugal.
When HR fails, people get lost.
Not physically. Usually.
A new hire shows up on Monday with no laptop, no login and no idea who their manager is. They spend the first week reading a handbook last updated when everyone still had a fax machine. By Friday, they’re already wondering if they made a mistake.
The world got more complicated, too. Your team might be spread across a bunch of states now, each with its own payroll taxes, leave rules and paperwork. Benefits got more complex. Compensation got more scrutinized. Getting any of it wrong costs money, and some of it costs a lot more than money.
But the biggest HR failure is the quiet one. The great employee who’s overloaded, under-recognized and invisible, until they hand in their notice. You’ll hear about it at the exit interview, if you do one. Most companies don’t.
When admin fails, the little things become big things.
The lease auto-renewed at a higher rate because nobody calendared the notice date. The insurance lapsed because the renewal went to someone who left. The client contract that was supposed to have a price increase built in doesn’t, and nobody can find the signed version anyway.
Admin is the most underrated function in any business. It’s the difference between “we’ve got that” and “who was supposed to handle that?”
A confession, since we’re being honest about bias
I’m not just preaching this. I’m living it.
FinStrat isn’t just me anymore, and growing it has thrown up all the same operational work I’ve watched clients wrestle with for years. So recently I brought in an outsourced operations team to help.
We did the discovery. We did the onboarding. And somewhere in there, I realized I wasn’t ready. My real bottleneck wasn’t operations support yet. I needed another accountant first. So I paused it, and I’ll revisit after the new year.
That’s the other lesson. Operations isn’t one thing you buy. It’s a set of functions you build, in the right order. Sequence matters as much as the investment. The finance guy almost got the sequence wrong. Imagine how easy it is for everyone else.
If any of this sounded familiar, you’re normal. You’re also at risk, and the risk grows every time revenue does.
Sales gets you the client. Operations is why you get to keep the business.
I’m biased. I’m also right. If you want help figuring out which operational gaps to close first, send me an email.
Want Monday Morning Business Tips in your inbox first? Sign up at the bottom of finstratcfo.com.
Thanks for reading FinStrat CFO! Subscribe for free to receive new posts and support my work.
Originally published on Substack.

Comments